
More news on this day
Recent changes to government travel advice for the United Arab Emirates have removed some of the starkest warnings about visiting the country, but conflicting insurance rules and war-related exclusions mean many travelers remain uncertain about what protection they actually have if their plans are disrupted.
Get the latest news straight to your inbox!
Advisories shift as tensions in the Gulf recalibrate
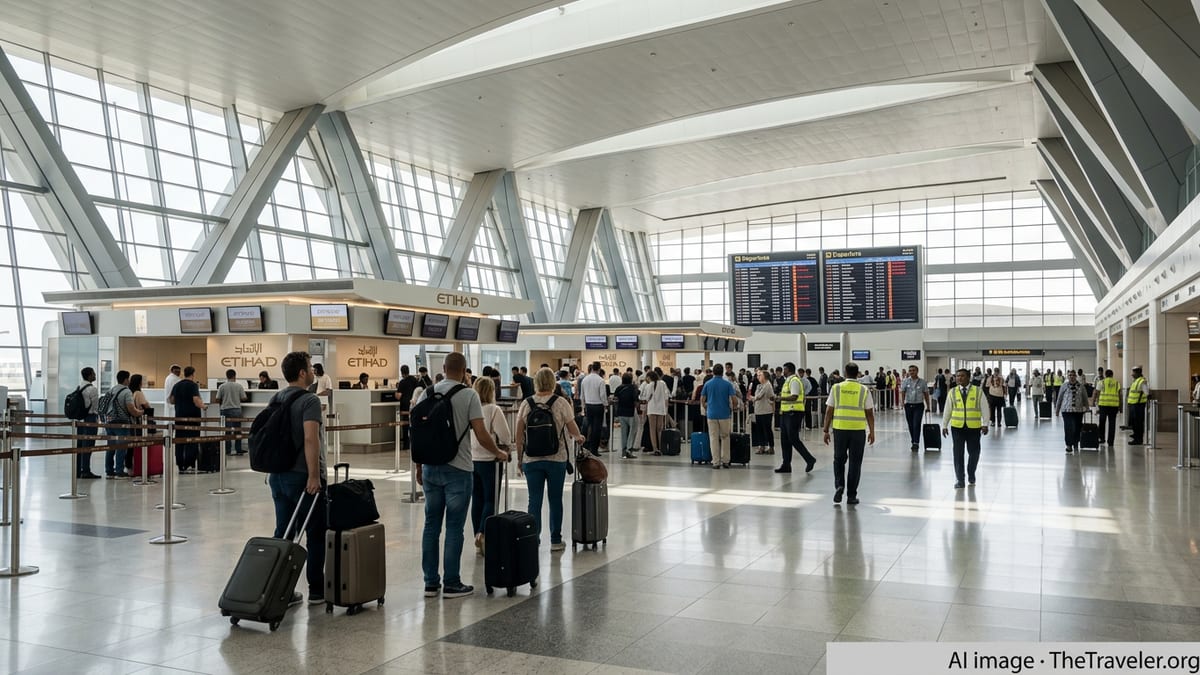
Publicly available government advisories show that perceptions of travel risk in the Gulf have evolved since the height of hostilities between the United States and Iran earlier in 2026. While the United States still rates the UAE at Level 3, meaning “Reconsider Travel,” its most recent advisory update on August 29, 2026, relaxed earlier restrictions by allowing family members of U.S. government staff to join them in the country. The overall risk level and references to terrorism and armed conflict remain, but the adjustment signals a more nuanced assessment of conditions.
Other governments have also revised their language on the Emirates. A widely discussed change in June, highlighted in traveler forums, followed an update from the United Kingdom’s Foreign, Commonwealth and Development Office that removed its previous “all but essential travel” stance for the UAE. That shift matters because many U.K. policies link coverage directly to FCDO wording, treating trips into “all but essential” or “do not travel” zones as grounds to deny claims.
Canada’s official advice, last updated on September 15, 2026, continues to warn that conflicts in the wider Middle East and Gulf region can affect the UAE, but it stops short of advising against travel. It instead urges visitors to ensure they have insurance that covers medical evacuation and hospital stays, emphasizing practical preparation rather than outright avoidance.
This gradual easing stands in contrast to travel warnings for nearby conflict areas, where both the U.S. State Department and European governments maintain “Do Not Travel” or high alert levels. The divergence highlights how regional instability can cast a long shadow over destinations that are not themselves active war zones, complicating both airline operations and insurance decisions.
Why the downgrade matters for insurance coverage
The language used in government advisories has an outsized impact on whether standard travel insurance remains valid. Guidance from the U.K. government makes clear that many policies can be invalidated if travelers enter a destination against formal advice such as “all travel” or “all but essential travel.” When the UAE was grouped more closely with higher-risk neighbors, this created a potential collision between holiday plans and small-print exclusions.
Specialist bulletins issued for U.K. travelers earlier in the year, as well as public-facing notices from major insurers, explain that most policies include a general exclusion for losses incurred while traveling contrary to foreign ministry advice. Some providers specify that if a warning is already in place when a policy is purchased, any claim linked to the underlying event may be rejected. That made it difficult for travelers who booked during quieter periods but saw the situation deteriorate before departure.
With the FCDO’s stance on the UAE softening, those particular exclusions may no longer apply to many trips that begin or connect through Dubai or Abu Dhabi. However, the U.S. Level 3 advisory and similar caution from other countries mean some insurers continue to take a conservative view, especially for policies sold in markets that emphasize U.S. State Department guidance or that maintain their own lists of higher-risk destinations.
As a result, a traveler departing from London and one departing from New York could face very different coverage outcomes for the same itinerary. In both cases, the change in official language improves the odds of securing full protection, but it does not guarantee that every policy will respond if tensions flare again.
War and terrorism exclusions still create major gaps
Even where travel to the UAE is no longer formally discouraged, questions remain about how standard insurance products respond to events linked to regional conflict. Industry briefings circulated in March and April by global underwriters and assistance firms underline that virtually all mass-market travel policies exclude “war” or “acts of war,” whether declared or undeclared. Many also exclude some terrorism-related losses, especially where there is an ongoing or widely reported conflict.
Customer notices released in early March 2026 by several international insurers outlined temporary suspensions or restrictions on new policies covering a long list of countries, including the United Arab Emirates, following the escalation of hostilities involving Iran. These notices typically clarified that existing policies would continue to apply subject to their terms, but that new cover for trips booked after a specified cut-off date might not respond to claims connected to the conflict.
Separate advisories from travel insurance brands tied to the Middle East crisis explain that travelers who simply “change their mind” about visiting a region after tensions increase are often not covered for cancellation, unless they purchased add-ons such as “Cancel for Any Reason.” In many cases, a policy will only respond if there is a direct impact, such as the traveler being personally injured, the airline canceling flights, or government-imposed closures that make the trip impossible.
This structure leaves a grey zone for travelers heading to the UAE: the country’s airports might be operating normally, yet airspace closures elsewhere, drone threats, or sudden rerouting around neighboring conflict zones could still cause delays, missed connections, or unscheduled stopovers. Unless those disruptions meet specific triggers written into the policy, the financial burden of rebooking or overnight stays may fall on the traveler rather than the insurer.
Airlines move to patch some of the protection gap
While traditional insurance products wrestle with war-related risks, some Gulf-based airlines have introduced their own solutions targeted at conflict-related disruption. In June 2026, Emirates announced what it describes as a comprehensive travel cover that includes medical protection for conflict-related incidents, as well as accommodation and extended-stay assistance in certain disruption scenarios. According to the airline’s public information, a key feature is that the cover applies regardless of government travel advice at the time of departure.
This approach reflects a broader trend of carriers stepping in where conventional insurance is constrained by exclusions. During earlier phases of the Middle East crisis, major airlines issued temporary waivers allowing passengers to rebook or receive credits when airspace closures or security concerns forced sudden route changes. Such waivers, however, are policy decisions rather than guaranteed rights, and they may not compensate for knock-on costs like missed tours or additional hotel nights.
Travel industry analyses published in May 2026 note that as long as Western government advisories remain elevated across parts of the region, many insurers will continue to treat travel there as an exceptional risk, even if UAE-specific warnings are relaxed. That tension creates an opening for airline-linked products that promise clearer, destination-specific guarantees, but also adds another layer of complexity for travelers trying to compare coverage options.
For now, airline-provided cover is best seen as a complement rather than a full replacement for standalone travel insurance. It can address certain conflict-related scenarios that traditional policies exclude, yet it may be limited to tickets issued by that carrier and to events occurring within a defined window around scheduled flights.
What travelers should scrutinize before booking the UAE
Consumer guidance from governments and insurance regulators consistently stresses the importance of reading policy wording in full, particularly for trips to regions affected by armed conflict. Official advice from the U.K. government on foreign travel insurance highlights the need to check clauses relating to war, terrorism, and travel against foreign ministry advice, and to confirm whether medical evacuation and hospital treatment in private facilities are included.
Industry notices produced in response to the Middle East crisis encourage travelers to pay special attention to the timing of their bookings. Policies may treat differently a trip purchased before a major escalation, one booked while severe warnings are in place, and another arranged after advisories have been partially downgraded. Cut-off dates listed in insurers’ public travel updates can determine whether a claim for cancellation or curtailment is accepted or rejected.
Specialist providers and brokers sometimes offer cover that remains valid even in destinations under higher-level advisories, but these products typically come with higher premiums or stricter conditions. Travelers whose plans involve transiting multiple hubs in the region, or visiting more than one country, may need to seek tailored policies that account for varied risk levels along the route.
Ultimately, the easing of government travel warnings for the UAE reduces one barrier to obtaining meaningful coverage, yet it does not erase the fundamental constraints that many insurers place on war-related events. Until there is sustained stability across the wider region, visitors to Dubai, Abu Dhabi, and other Emirates are likely to face a patchwork of protections, making careful comparison of policy terms as essential as checking flight schedules or visa rules.