
More news on this day
Neurodivergent holidaymakers are being urged to review travel insurance declarations after UK industry data and consumer reports indicated a sharp rise in disclosures related to conditions such as autism and ADHD, alongside growing confusion over what must be declared to keep policies valid.
Get the latest news straight to your inbox!
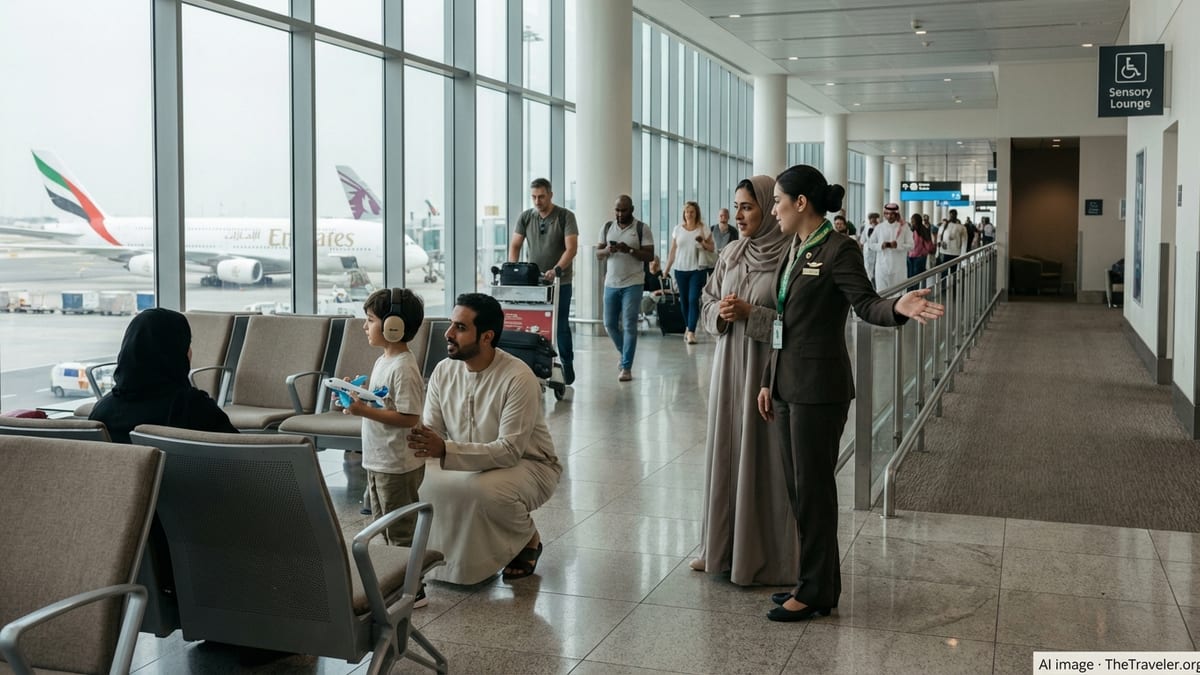
Holiday medical declarations surge for neurodivergent conditions
Travel insurance providers and consumer organisations in the UK report that medical declarations linked to neurodivergent and mental health conditions have increased significantly over the past year, mirroring a wider rise in diagnosis and treatment. Publicly available commentary from specialist insurers shows more customers disclosing autism, ADHD and related conditions when buying annual multi-trip and single-trip policies, with some firms describing a doubling of such declarations compared with pre‑pandemic levels.
Published guidance from the UK government on foreign travel insurance stresses that all pre-existing medical conditions, including mental health and neurological conditions, must be declared at the point of purchase, or travellers risk invalidating their cover. The advice highlights that some insurers exclude or limit cover for treatment linked to pre-existing mental health conditions, making accurate disclosure essential where support needs might affect a trip.
Advisory services such as MoneyHelper note that insurers typically ask about any medical or psychological condition for which a traveller has received treatment, investigations or prescribed medication within a set period, often the previous two years. That scope can include neurodevelopmental diagnoses, assessments in progress, or medication reviews, which is leading many neurodivergent travellers to face more complex online screening questionnaires than in the past.
Specialist medical travel providers state that they can insure a wide range of neurological and psychological conditions, but that higher risk profiles and complex histories can result in increased premiums or exclusions. Consumer-facing material from disability and mental health organisations indicates that, while access to cover has improved in some areas, neurodivergent travellers still frequently encounter higher prices, restricted options or outright refusals when they attempt full disclosure.
Signposting rules and the FCA focus on pre-existing conditions
The UK Financial Conduct Authority (FCA) has introduced and refined signposting rules designed to help people with serious pre-existing medical conditions find suitable travel insurance. A post‑implementation review published in April 2024 reported that the rules have led to more consumers being directed towards specialist providers where mainstream insurers view the medical risk as too high.
The rules require insurers to alert customers to a directory of specialist firms when quotes include a significant loading to cover medical conditions, or where customers are declined or offered policies with blanket exclusions. Subsequent FCA consultations and handbook updates have focused on refining how the trigger premium is calculated, with the stated aim of maintaining access for those with higher‑risk conditions while avoiding disproportionate barriers.
Within this framework, mental health and neurodevelopmental conditions are treated as pre-existing medical conditions when they meet the criteria set out in policy wording. Research summarised in the FCA review, alongside reports from consumer groups, shows that people with mental health difficulties often face higher premiums, reduced cover or refusals when they declare their conditions. Advocacy organisations argue that many neurodivergent travellers experience similar challenges, particularly where medication, behavioural support needs or co‑occurring mental health issues are involved.
Although the signposting rules are not specific to neurodivergent conditions, advisers suggest they are increasingly relevant for this group as diagnoses become more common and more people seek to travel with tailored support. The key practical impact is that travellers who receive very high quotes or exclusions may be pointed towards specialist brokers and insurers that are better equipped to assess complex neurodevelopmental and mental health histories.
Disclosure dilemmas: waiting lists, undiagnosed issues and mental health clauses
Consumer advice outlets report that many UK travellers are uncertain about what must be declared when they are on a waiting list for assessment or treatment related to neurodivergent conditions. Recent coverage from Which? explains that insurers generally expect disclosure of symptoms or conditions that are under investigation, even if no formal diagnosis has been made. Industry examples show that failure to mention an ongoing referral, investigation or medication review can later be cited as a reason to reduce or reject a claim.
Policy documents and online medical screening forms frequently use broad language, asking whether travellers have any medical or psychological condition that has required treatment, tests or investigations in the specified time frame. Anecdotal accounts gathered by charities and online forums indicate that this can capture people awaiting autism or ADHD assessments, as well as those undergoing mental health medication reviews linked to their neurodivergent profile.
Consumer information from UK travel insurance brands notes that ADHD, autism and similar conditions are usually insurable when declared, but travellers may have to answer detailed questions about how the condition affects daily life, whether it has led to trip cancellations in the past, and whether they can travel independently. Some mainstream insurers indicate that they may decline cover or cancel policies where an individual is in the middle of a lengthy review or investigation of their mental health or medication, steering them instead towards specialist providers.
Guidance from government travel health sources and charitable organisations consistently advises against omitting or downplaying such information. They emphasise that under UK insurance law, inaccurate or incomplete answers to specific medical questions can allow insurers to alter or void policies. For neurodivergent travellers, the combination of broad mental health questions and long NHS waiting times for assessment can therefore create difficult choices if travel is planned before investigations are complete.
Impact on premiums, access to cover and holiday planning
Although there is no single published figure on average premium changes for neurodivergent travellers, evidence from specialist insurance guides and consumer case studies suggests that full disclosure often results in higher prices or tighter conditions. Examples from UK comparison tools and disability advice pages show that adding mental health or neurodevelopmental diagnoses to a quote can increase premiums compared with policies that do not include these details, even when the traveller has no history of cancelling trips or needing emergency care abroad.
Some insurers advertise that they will cover autism or ADHD at no extra cost where the traveller confirms they can manage travel independently, have not had recent related hospital admissions and have never had to curtail a holiday for that reason. Other providers classify neurodivergent and mental health conditions within broader high‑risk categories, which can lead to substantial premium loadings or requirements to buy from a specialist broker rather than a standard online policy.
Consumer organisations warn that, despite higher costs, travellers should not be tempted to withhold details in order to secure cheaper cover. Government travel advisories reiterate that emergency medical expenses overseas can run into tens or hundreds of thousands of pounds, and that even state‑backed schemes such as the UK Global Health Insurance Card are not a substitute for comprehensive insurance. Without a valid policy that reflects a traveller’s full medical history, families may have to meet treatment, repatriation and accommodation costs themselves if complications arise.
For neurodivergent travellers and their families, this environment is shaping holiday planning decisions. Published guidance encourages buying insurance as soon as a trip is booked, carefully reading mental health and neurological condition sections in medical questionnaires, and contacting insurers for clarification where questions are unclear. Some charities recommend working with specialist brokers who routinely handle complex neurological and psychological profiles, which can reduce the risk of misunderstandings and offer clearer explanations of what is and is not covered.
Calls for clearer wording and better protections for neurodivergent travellers
As declarations related to neurodivergent and mental health conditions increase, disability and mental health advocacy groups are pressing for clearer, more standardised medical questions in travel insurance. Reports highlight that many travellers struggle to understand whether broad references to psychological or neurological conditions apply to their situation, especially when they feel well and do not anticipate needing support on holiday.
Organisations working with disabled travellers argue that more precise wording could help people answer accurately without unnecessary alarm, and reduce the risk of inadvertent non‑disclosure. They also call for insurers to distinguish more clearly between conditions that significantly increase the risk of claims and those that do not materially affect travel, to avoid pricing people out of cover solely on the basis of diagnosis.
Regulatory material from the FCA indicates a continuing focus on fairness for customers with health conditions, including mental health and cognitive difficulties. While current signposting rules are framed around pre-existing medical conditions broadly, consumer advocates are urging regulators and industry bodies to examine how these protections operate in practice for neurodivergent travellers who may face both higher premiums and communication barriers.
Until any new measures are agreed, publicly available advice for neurodivergent holidaymakers remains consistent: declare all relevant diagnoses, investigations and medication, check policies carefully for mental health and neurological exclusions, and seek specialist guidance where standard online forms do not appear to reflect individual needs. With holiday medical declarations for neurodivergent conditions rising, the risk of travellers being left without effective cover if something goes wrong is increasingly in focus.