
Choosing travel insurance is rarely simple, especially if you are older, managing a medical condition or planning a more complex trip like a cruise or a long winter escape. Avanti Travel Insurance, a UK-based specialist, has built its reputation around these exact scenarios, offering cover that aims to go further than many standard comparison-site policies. Understanding who benefits most from Avanti can help you decide if it is the right fit for your next journey.
Get the latest updates straight to your inbox!
Understanding Avanti’s Niche in the Travel Insurance Market
Avanti Travel Insurance is a UK-focused provider whose policies are particularly known for accommodating pre-existing medical conditions and older travelers. Rather than chasing the lowest possible premiums, Avanti positions itself as a specialist option for people who struggle to get adequate protection elsewhere. Its marketing and product design are built around customers who might have been declined or heavily restricted by mainstream insurers.
On Avanti’s own site, the company highlights that it can consider cover for over 1,300 medical conditions, subject to medical screening, with no automatic upper age limit on many single-trip policies for UK residents. It also emphasizes high medical expense limits and comprehensive emergency assistance. For example, recent independent reviews of Avanti’s policies note that its Deluxe level can offer unlimited emergency medical and repatriation cover and higher cancellation limits than its entry-level options, which can be significant for long-haul holidays or cruises.
The trade-off is that Avanti is often not the cheapest quote you will see on comparison engines. Instead, its value lies in what it will actually pay for if something goes wrong, particularly when medical history is involved. This makes Avanti especially relevant for travelers who care more about robust protection than shaving a few pounds off the premium.
To understand whether Avanti is right for you, it helps to look at the groups of travelers who typically benefit most from its approach: older holidaymakers, people with medical conditions, frequent cruisers, and those planning higher-value trips where cancellation or medical evacuation costs could be catastrophic without proper cover.
Older Travelers Who Want Comprehensive, Age-Friendly Cover
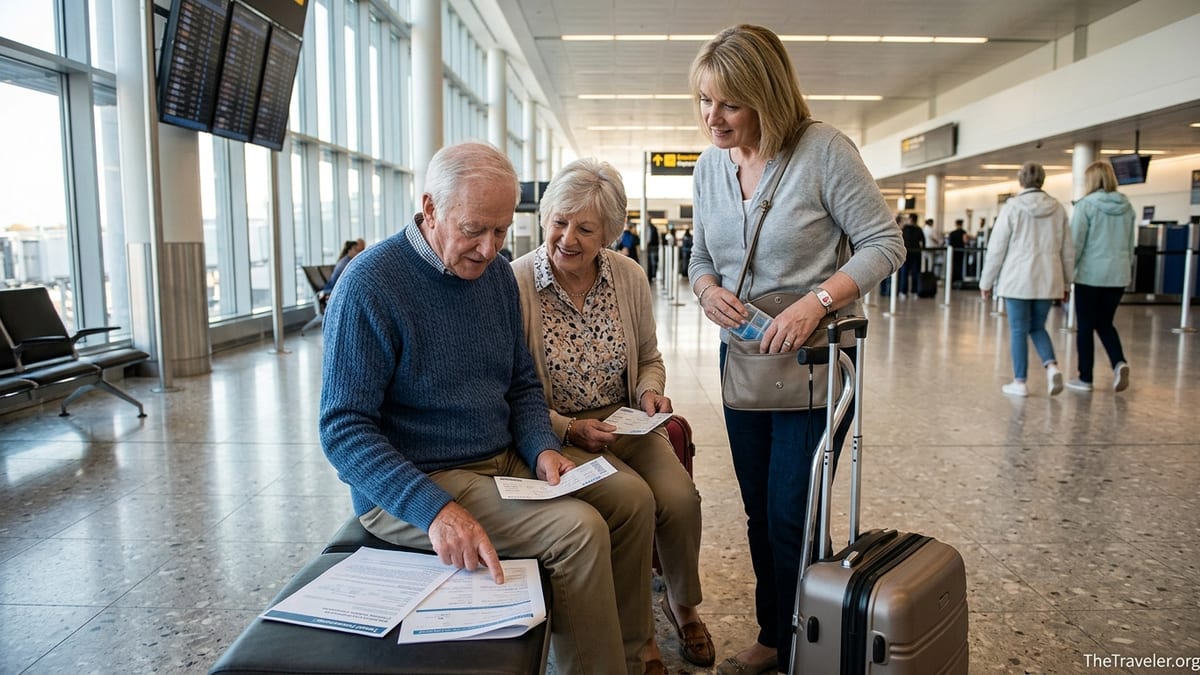
One of Avanti’s strongest niches is older travelers, including those over 70 or 80, who often find that standard insurers either charge steep premiums or refuse to quote at all. Information on specialist comparison sites shows Avanti listed among the providers willing to consider cover up to age 85 for various trip types, and Avanti’s own seniors-focused pages stress that cover can be available at “any age” on certain products, subject to medical screening and policy type.
Consider a 78-year-old couple from Manchester planning a two-week winter break in Tenerife. They want cover for emergency medical treatment in Spain, cancellation, lost baggage and travel disruption. A basic comparison-site policy might appear cheaper at first glance but come with strict age caps, low medical limits or a refusal to cover existing conditions like high blood pressure or mild heart disease. An Avanti specialist seniors policy, after screening, may cost more upfront but is more likely to provide high medical expense limits, cover for declared conditions and 24/7 emergency assistance including repatriation to the UK if needed.
Another typical example is a solo 82-year-old traveler visiting family in Canada for three weeks. Some mainstream insurers impose upper age limits for long-stay trips, especially outside Europe. Avanti’s literature and independent reviews highlight that it aims to accommodate longer trips and long-haul destinations for older age groups, provided the customer passes the medical screening and meets stability requirements. For such a traveler, Avanti can be one of the few realistic options that do not automatically exclude them purely based on age.
For older travelers, the real-world value is less about small differences in price and more about whether the policy will respond if a chronic condition flares up, a fall results in a hospital stay or a family emergency back home requires cutting the trip short. Avanti’s orientation toward seniors makes it a strong candidate when those risks are front of mind.
Travelers With Pre-Existing Medical Conditions
Avanti’s clearest advantage is for people who have pre-existing medical conditions and want those conditions properly covered, not quietly excluded in the small print. The company states that it can consider more than 1,300 conditions, including common issues such as diabetes, high blood pressure, heart conditions, asthma, various forms of cancer in remission and digestive conditions like Crohn’s disease or ulcerative colitis, subject to medical screening and underwriting.
Imagine a 64-year-old traveler with type 2 diabetes, controlled high blood pressure and a history of minor angina, planning a ten-day city break to New York. Many mainstream policies will either decline cover outright or offer a cheap premium that excludes any claim linked to these conditions. That might still leave the traveler covered if they break an ankle while sightseeing, but not if they are hospitalized due to a cardiac issue. By contrast, Avanti’s model is to ask detailed medical questions online or by phone, rate the risk, and then confirm in writing which conditions are covered. The premium may be higher, but the traveler gains the reassurance that a heart-related hospital stay in the United States, where costs can easily run to tens of thousands of pounds, is within the scope of the policy.
Another example is a 55-year-old breast cancer survivor whose treatment ended two years ago and who is planning a Mediterranean cruise. Some policies treat any past cancer as a reason to decline or exclude related claims. Avanti’s medical-conditions-focused marketing suggests that it will consider many cancer histories on a case-by-case basis, again with the crucial requirement that full disclosure is made and cover is explicitly agreed. For that traveler, Avanti can be the difference between being able to book with confidence and feeling forced to travel uninsured for the very risk that most worries them.
However, it is equally important to understand Avanti’s limits. Policy documents and key facts summaries make clear that cover may not be available where someone is travelling against medical advice, awaiting test results or surgery, undergoing certain forms of active cancer treatment or has been given a terminal prognosis, unless the insurer has specifically agreed otherwise and listed it on the policy certificate. This is standard practice across the industry, but Avanti’s emphasis on medical risk means it will often be clearer and more explicit about what is and is not allowed.
Cruise Passengers and Complex Itineraries
Cruise travel combines multiple moving parts: flights, connecting transfers, time-sensitive ship departures and visits to several different countries on a single trip. Missed departures or serious illness at sea can become very expensive, especially if a medical evacuation or a mid-cruise flight home is required. Specialist cruise cover is an area where Avanti can be attractive for certain travelers, especially older passengers or those with pre-existing conditions.
Consider a couple in their early seventies booking a 14-night Mediterranean cruise departing from Southampton with stops in Spain, Italy and Greece. The total trip value might be around £4,000 to £6,000 including the cabin, onboard packages and prepaid excursions. A standard low-cost travel policy may cover cruises only in a limited way or treat them as a standard package holiday, without specific protections for missed ports, cabin confinement or unused excursions. Avanti policies with cruise options are designed with these risks in mind, often including cruise-specific benefits as standard or as an add-on, such as cover for missed port departures due to breakdowns or delays, and contributions toward on-board medical costs, which are usually private and can be charged in foreign currency.
Similarly, travelers taking more complex itineraries, such as a multi-centre trip combining a European city break with a river cruise and a week in a beach resort, often benefit from the higher cancellation limits and emergency medical cover at Avanti’s Classic or Deluxe levels. Independent reviews have noted that, for example, medical limits on Classic can reach into the tens of millions of pounds, with Deluxe sometimes offering unlimited medical cover. For someone stitching together several non-refundable elements, investing in a policy geared to high medical and cancellation limits can be a rational choice.
Where Avanti’s cruise proposition is especially strong is when a passenger has medical conditions that many mainstream cruise-policy providers decline to cover. As with its land-based policies, detailed screening is required, and there will be situations where cover cannot be offered. But for a large number of older cruisers with stable, managed conditions, Avanti offers a route to travel with cover that more closely reflects the real risk profile of being at sea.
Long-Stay, Multi-Trip and High-Value Holidays
Beyond age and health, Avanti can also be a good match for people planning long-stay holidays, frequent travel or particularly high-value trips. While exact products and terms evolve, Avanti and related specialist brands have historically offered annual multi-trip policies and extended single-trip durations that cater to retirees spending winters abroad or professionals making several long-haul journeys each year.
Take the example of a 67-year-old retired teacher who spends up to 60 days at a time in Portugal each winter. Some budget insurers cap single-trip durations at 31 days or impose stricter age limits on policies that allow longer stays. Avanti’s policy documents and marketing for long-stay and annual products often allow longer maximum trip lengths for older ages, subject to underwriting and destination. This can reduce the need to stitch together multiple short policies or risk being left uncovered for the last weeks of a trip.
For business owners or families booking complex, expensive itineraries, Avanti’s higher cancellation and curtailment limits may also be appealing. For example, Deluxe-level cover is sometimes referenced in independent reviews as allowing cancellation cover in the region of £7,500 per person on certain policy versions, compared with lower limits of around £1,000 on entry-level Essentials cover. If a family of four spends £10,000 on a three-week tour of Australia, including internal flights and pre-paid excursions, a higher-tier Avanti policy is more likely to align with the true financial exposure than a bare-bones alternative.
It is worth noting that premiums for long-stay and high-value cover can rise quickly once pre-existing conditions and age are factored in. Avanti is not automatically the cheapest choice for globetrotters whose health is excellent and who are under 50. But for those combining extended durations, significant prepaid costs and a complex medical history, Avanti can strike a pragmatic balance between price and peace of mind.
Who Might Not Be the Best Fit for Avanti?
While Avanti suits many higher-risk or more complex travelers, there are scenarios where other insurers or even free packaged-account cover might be a better fit. Younger, healthy backpackers on tight budgets, for instance, may find that Avanti’s medically focused, higher-limit structure offers benefits they are unlikely to use and cannot justify on cost grounds.
A 25-year-old graduate taking a three-week interrail trip across central Europe, with no medical conditions and total prepaid costs under £1,000, may find many mainstream policies with adequate medical limits and basic gadget cover for a significantly lower premium than a specialist policy. In that case, the main risks are likely to be lost belongings, minor injuries or travel delays, which standard mass-market policies can cover reasonably well, so long as the traveler reads the exclusions carefully.
Avanti may also not be ideal for those who are travelling primarily for medical treatment abroad or whose conditions are currently unstable, awaiting surgery or under active investigation. As with most insurers, Avanti’s terms generally exclude cover when a person is travelling against medical advice, has a terminal prognosis or is undergoing certain intensive treatments, unless explicitly agreed in advance. In these complex medical-tourism scenarios, specialist international health insurance or bespoke high-risk solutions might be more appropriate than standard travel insurance.
Finally, travelers based outside the UK should be aware that Avanti’s core travel insurance products are targeted at UK residents and regulated accordingly. While people may encounter the Avanti name in other contexts, such as separate travel protection plans tied to tour operators, those products have different underwriters and conditions. Non-UK residents should seek local equivalents that follow a similar philosophy of detailed medical screening and higher medical limits, rather than assuming the UK-targeted Avanti product is available to them.
How Avanti Compares in Real-World Scenarios
To understand who benefits most from Avanti, it helps to compare realistic scenarios side by side with a more generic insurer. Consider two travelers booking a week in Florida at £2,000 each: a 45-year-old with no medical history and a 73-year-old with controlled high blood pressure and type 2 diabetes. Both want £10 million or more in emergency medical cover and solid cancellation protection.
The 45-year-old can likely buy a mainstream policy with high medical limits and standard cancellation for a modest premium, because their risk profile is low. A standard insurer sees them as a straightforward case. Avanti could still cover them, but it may not offer a distinct advantage beyond customer service preferences.
The 73-year-old, however, will often find that generic policies either refuse to cover their pre-existing conditions or ask them to sign up at a much higher premium with significant exclusions. Avanti, by design, invites them to declare and screen those conditions in detail. The resulting premium is likely to be higher than the 45-year-old’s, but the difference is tied directly to covering real medical risk. If that traveler ends up in a Florida hospital for complications related to diabetes or blood pressure, an Avanti policy that specifically lists those conditions as covered can be crucial.
Another scenario is a 60-year-old booking a Norwegian fjords cruise costing £3,500, including flights and two nights in a hotel before embarkation. A basic policy might cover cruise travel incidentally but not offer benefits for missed ports, cabin confinement due to illness or missed departure if a connecting flight is delayed. An Avanti policy with cruise cover and higher cancellation limits is more likely to provide tailored protections, which become highly relevant if bad weather or a medical issue forces itinerary changes.
In each of these comparisons, Avanti’s value emerges most clearly for people whose age, health or trip complexity place them outside the profile that budget-oriented insurers are built around. For mainstream, low-risk trips, Avanti is a solid but sometimes more expensive option. For higher-risk profiles, it can be one of the few providers offering meaningful, medically aware protection.
The Takeaway
Avanti Travel Insurance is best thought of as a specialist option rather than a one-size-fits-all solution. Its strongest benefits are reserved for travelers who either struggle to find good cover elsewhere or whose personal situation makes robust medical protection more important than a rock-bottom premium. Older travelers, people with pre-existing medical conditions, cruise passengers and those embarking on long-stay or high-value holidays are the groups that stand to gain most from Avanti’s approach.
For a healthy 30-year-old going on a low-cost weekend break, Avanti might be more cover than they realistically need. But for a 72-year-old with stable heart disease flying to North America, or a 65-year-old cancer survivor about to board a Mediterranean cruise, the combination of detailed medical screening, high medical and cancellation limits, and tailored cruise or long-stay features can provide a level of reassurance that cheaper policies cannot match.
Ultimately, deciding whether Avanti is right for you means weighing your age, health, destination and trip value against the cover levels and exclusions of different policies. Reading the key facts documents carefully, declaring all medical conditions honestly and comparing like-for-like limits will help you see whether Avanti’s specialist focus offers genuine value for your particular journey.
FAQ
Q1. Is Avanti Travel Insurance only for older travelers?
Avanti is well known for covering older travelers, including people over 70 or 80, but it is not limited to them. It will also insure younger adults and families, particularly when medical conditions need to be covered. The main difference is that Avanti’s products are designed with older and medically complex travelers firmly in mind.
Q2. Does Avanti cover pre-existing medical conditions?
Yes, Avanti is specifically set up to consider a wide range of pre-existing medical conditions, subject to medical screening and underwriting. Customers must declare all relevant conditions during the quote process and wait for written confirmation that those conditions are covered on the policy certificate.
Q3. Will Avanti cover me if I am awaiting tests or surgery?
In many cases, standard Avanti policies do not cover people who are awaiting test results, surgery or treatment, or whose condition is unstable, unless the insurer has explicitly agreed to do so. If you are in this position, you should speak directly to Avanti and review the wording carefully before relying on any policy.
Q4. Is Avanti the cheapest option for travel insurance?
Avanti is rarely the very cheapest option, especially for younger, healthy travelers taking low-cost trips. Its premiums are often higher because they reflect higher levels of medical cover and the additional risk associated with older ages and medical conditions. For some travelers, this extra cost buys meaningful additional security.
Q5. Are cruises automatically covered by Avanti policies?
Not always. Some Avanti policies include cruise cover as standard, while others require you to add cruise cover as an optional extra. If you are booking a cruise, it is important to select a product that explicitly mentions cruise benefits, such as cover for missed port departures or cabin confinement.
Q6. Can non-UK residents buy Avanti Travel Insurance?
Avanti’s core travel insurance products are aimed at UK residents who are registered with a UK doctor and meet specific residency criteria. Non-UK residents generally cannot buy the same policies and should look for equivalent providers in their own markets.
Q7. Does Avanti cover COVID-19 related claims?
Avanti has offered varying levels of COVID-19 cover over time, typically including some protection for emergency medical costs and, in certain circumstances, cancellation if you test positive before travel. Because details change, you should check the most recent policy wording to see exactly what COVID-19 related events are covered when you buy.
Q8. What levels of cover does Avanti offer?
Avanti usually offers tiered levels such as Essentials, Classic and Deluxe, each with different limits for cancellation, baggage and medical expenses. Higher tiers tend to offer larger cancellation limits and higher or even unlimited medical cover, at a higher premium. The right level depends on your trip value, destination and personal risk tolerance.
Q9. How does medical screening work with Avanti?
Medical screening with Avanti typically involves answering detailed health questions online or over the phone about diagnoses, medications, treatments and recent changes in your condition. The answers help the insurer assess risk and determine whether it can cover your conditions, on what terms and at what price. It is vital to answer truthfully and completely.
Q10. When should I buy an Avanti policy for maximum protection?
You should usually buy your Avanti policy as soon as you book your trip, so that cancellation cover starts immediately. This way, if a covered event forces you to cancel before departure, you are more likely to be protected for non-refundable costs. Waiting until just before you travel can leave you exposed if something happens in the meantime.