
More news on this day
A wave of mega projects stretching from the Gulf to the Pacific is turning Asia into the world’s most ambitious tourism construction zone, as governments and investors channel an estimated 1 trillion dollars into destinations designed to capture the next generation of global travelers.
Get the latest news straight to your inbox!
Saudi Arabia Leads with Giga-Projects and Capital Commitments
In the Gulf, Saudi Arabia has emerged as the most visible symbol of Asia’s tourism ambitions, tying its economic diversification agenda directly to large-scale destination development. Public investment documents and promotional materials indicate that the kingdom is targeting 150 million domestic and international visits annually by 2030, with tourism expected to contribute around 10 percent of gross domestic product. The strategy is supported by a hotel pipeline projected to exceed half a million rooms, alongside extensive new transport and urban infrastructure.
Within that framework, so-called giga-projects such as NEOM, The Red Sea, Amaala, Qiddiya, AlUla and Diriyah are being built as stand-alone tourism ecosystems. Investment research summarizing the program points to a combined capital outlay that already surpasses 500 billion dollars across these flagship sites, with total tourism-related investment commitments in the country frequently described in regional analysis as approaching the 1 trillion dollar mark when supporting infrastructure and private-sector projects are included.
Much of the early focus is on luxury and experience-led travel, with resort clusters, heritage districts and entertainment hubs meant to attract high-spending visitors who might once have headed to Europe or North America. At the same time, official investment promotion materials emphasize a structural shortage of midscale and budget accommodation, positioning this segment as a major opportunity for international operators and developers as visitor volumes expand.
The scale of construction is reshaping regional travel flows. Airlines and cruise operators are adjusting capacity to account for future demand from the Red Sea coast and Arabian Gulf, while neighboring countries are exploring joint itineraries that combine cultural, religious and leisure travel across borders.
China’s Travel Rebound Repositions Outbound and Domestic Markets
Further east, China’s tourism profile is being redefined by the recovery of both domestic and outbound travel. Data from government and industry platforms show that the country recorded more than 5.6 billion domestic trips in 2024, a double-digit increase on the previous year that pushed volumes close to pre-pandemic levels. Analysts point to a rapid rebound in spending on leisure, short breaks and family travel, supported by expanding high-speed rail networks and the continued build-out of theme parks and cultural attractions.
Outbound tourism from China is also regaining its former position as a critical driver of global travel demand. Research on 2024 and early 2025 performance highlights a full-fledged recovery in regional trips, particularly to destinations such as Hong Kong, Macao and cities across Southeast Asia. Many of these markets are recalibrating marketing campaigns, payment options and air service agreements to capture Chinese visitors who are returning with new expectations after several years of constrained mobility.
On the inbound side, authorities have moved to relax visa requirements and expand unilateral visa-free policies for a growing list of countries. An annual report on inbound tourism development published in Beijing in 2024 noted that visa, payment and accommodation facilitation measures were beginning to translate into more visible foreign visitor growth, with expectations that volumes would fully recover from the pandemic impact in the near term.
These shifts mean China is simultaneously an investor, a destination and a key source market in the emerging 1 trillion dollar tourism landscape. Chinese companies are participating in overseas resort, aviation and urban projects, while domestic provinces compete to capture a larger share of internal travel spending through new cultural districts, mountain resorts and coastal leisure zones.
Indonesia Builds New Tourism Hubs from Bali to Nusantara
Indonesia is advancing its own tourism transformation, anchored by both established destinations and entirely new urban developments. Bali remains the country’s flagship international gateway, but recent government and state-owned enterprise communications emphasize a pivot toward higher-yield, more sustainable tourism. In the Nusa Dua area, the InJourney Tourism Development Corporation has highlighted investments in integrated waste management, water recycling and smart utilities as part of a green-infrastructure upgrade meant to position the enclave as a model for low-impact, high-value resort zones.
Beyond the island, the construction of the new national capital, Nusantara, on the island of Borneo is being framed as a long-term tourism and investment play. Official descriptions of the project outline economic clusters that include ecotourism and health tourism alongside clean technology and sustainable agriculture. The new city is billed as a green and smart urban center, drawing visitors for both business and leisure and relieving environmental pressure on Jakarta.
Research into land-use change around Nusantara shows rapid development in core government areas, prompting questions about how the “forest city” vision will balance infrastructure needs with conservation. At the same time, the site has already started to attract domestic visitors, with reported daily arrivals in the low thousands, indicating early interest in the emerging destination and its surrounding natural landscapes.
Indonesia’s broader tourism investment program includes the enhancement of other priority destinations, from Mandalika in Lombok to health tourism zones in Bali and beyond. Central bank and planning documents have linked these initiatives to wider goals of boosting foreign exchange earnings, spreading visitor traffic beyond a handful of hotspots and strengthening regional connectivity across the archipelago.
Regional Competition and Collaboration Redraw Global Travel Flows
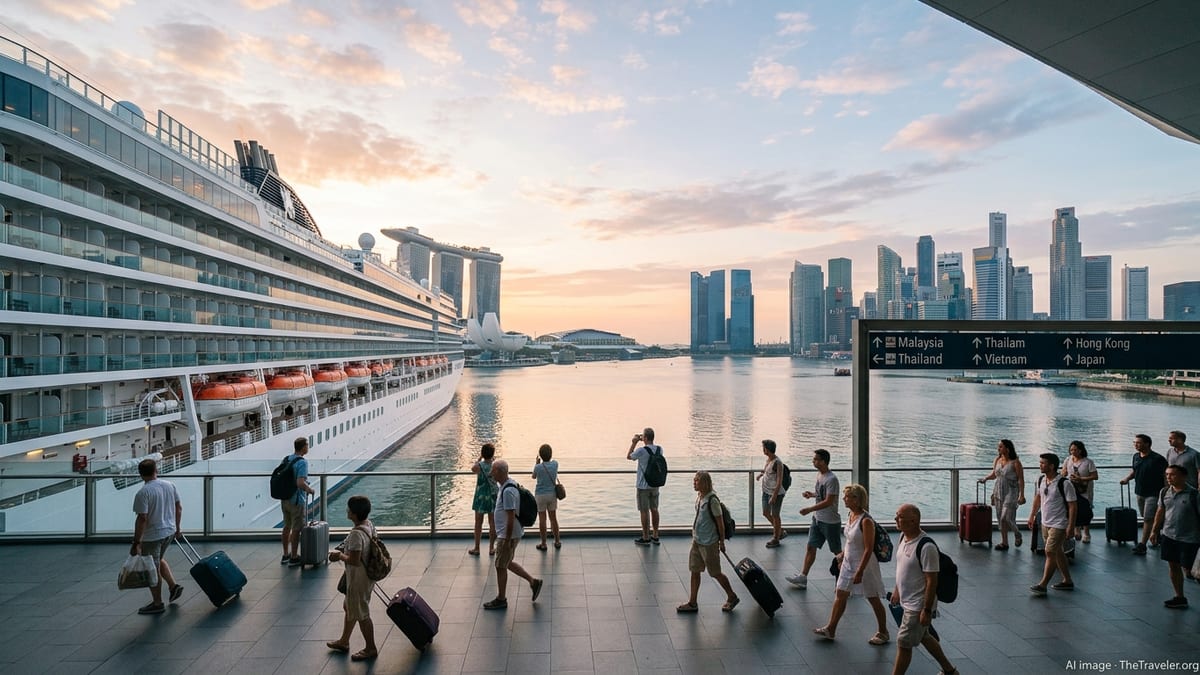
The surge in tourism capital deployment is creating a more competitive landscape within Asia itself. Saudi Arabia is vying with traditional Gulf hubs such as Dubai and Abu Dhabi for long-haul European and North American travelers, while simultaneously courting visitors from China, India and Southeast Asia. In parallel, countries like Indonesia, Thailand and Vietnam continue to invest in airports, cruise terminals and resort infrastructure to retain their appeal as mass-market holiday destinations.
Analysts note that the new wave of projects is not limited to bricks and mortar. Investment roadmaps highlight spending on tourism technology platforms, smart-city systems and experience design, from seamless biometric border control to integrated booking and payment ecosystems. These digital layers are intended to differentiate destinations and make it easier for travelers to navigate multi-country itineraries across Asia.
Collaboration is emerging alongside competition. Aviation partnerships, open-skies discussions and shared visa schemes are being explored or expanded in subregions such as the Gulf and Southeast Asia, with the goal of encouraging visitors to extend stays and explore multiple countries in a single trip. Cruise operators are planning routes that connect newly developed ports on the Red Sea, the Indian Ocean and the Western Pacific, reflecting confidence that infrastructure will keep pace with capacity growth.
For long-haul travelers from Europe and the Americas, the effect is a wider array of choice and potentially new patterns of travel. Multi-stop journeys that combine cultural heritage in the Middle East, beach resorts in Southeast Asia and urban experiences in East Asia are expected to become more common as connectivity improves and marketing campaigns are increasingly coordinated across borders.
Sustainability, Risk and the Long-Term Tourism Bet
The sheer scale of Asia’s tourism build-out has raised questions about sustainability, climate resilience and financial risk. Mega-resorts, desert cities and coastal developments require significant water, energy and transport infrastructure, much of it in environments already facing stress from rising temperatures and sea-level concerns. Environmental groups and academic researchers have flagged the need for robust impact assessments and adaptive design, particularly in sensitive marine and forest areas.
Destination planners are responding with language that emphasizes green building standards, renewable energy integration and circular-economy principles, as seen in initiatives such as integrated waste management in Bali’s Nusa Dua and smart-city blueprints for Nusantara. Whether these frameworks can be fully implemented at the pace and scale of construction remains a central question for investors and communities alike.
Financially, the 1 trillion dollar figure often cited in analysis of Asian tourism investment encompasses not only headline resort projects but also airports, rail links, ports and urban services that depend on sustained demand growth. Any prolonged shock to global travel, shifts in consumer preference or geopolitical tension could test the resilience of business models that assume steadily rising visitor numbers and higher average spend per trip.
Even so, governments and investors show little sign of retreating from tourism as a pillar of long-term development. Publicly available strategies across Saudi Arabia, China and Indonesia position travel and hospitality as engines of job creation, urban renewal and soft power. For travelers, the result is a rapidly evolving map of options, as Asia’s tourism giants seek to turn unprecedented capital commitments into enduring destinations.