
More news on this day
A sharp rise in UK holidaymakers declaring ADHD and autism to travel insurers has prompted renewed warnings that neurodivergent travellers risk invalidating their policies if they fail to disclose diagnoses or ongoing assessments.
Get the latest news straight to your inbox!
Declarations surge as older travellers disclose ADHD and autism
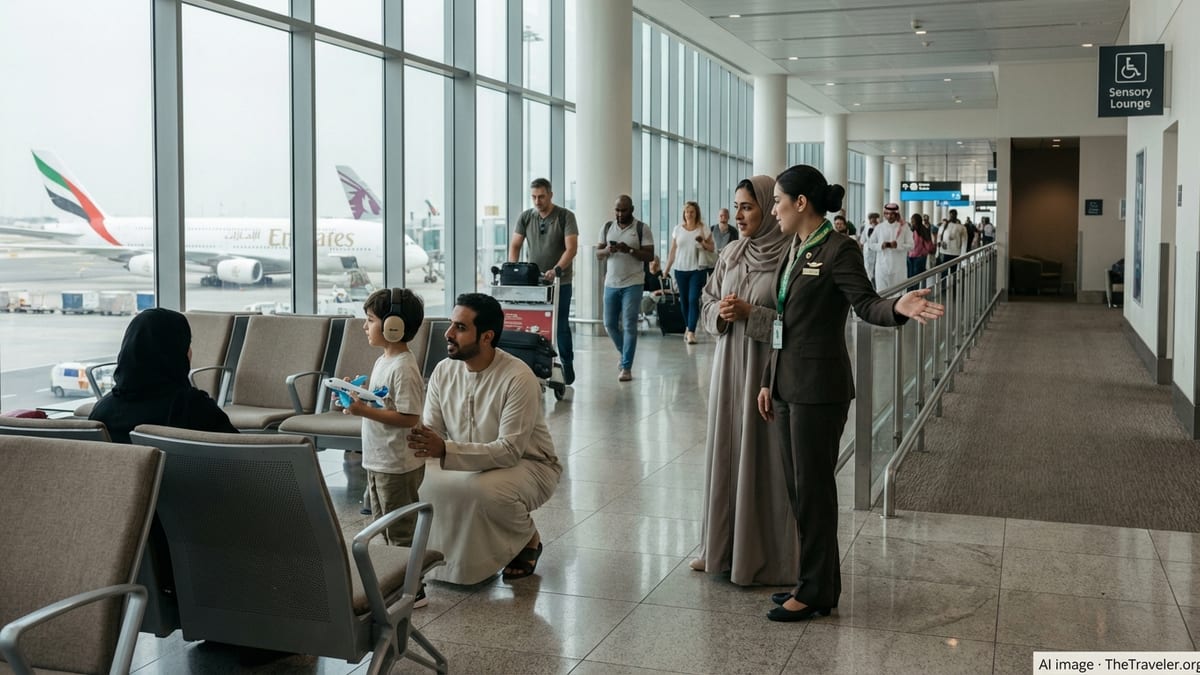
Recent coverage in specialist industry outlets indicates that declarations of ADHD and autism on UK travel insurance policies have nearly doubled within a year, particularly among customers over 50. One report citing data from insurer Staysure found that declarations of ADHD and autism among its over-50s customers reached 4,676 between January and July 2026, compared with 2,613 during the whole of 2025. The figures highlight both rising diagnosis rates in later life and growing awareness that neurodivergent conditions can count as pre-existing medical conditions for insurance purposes.
Analysts note that this increase is occurring against a wider backdrop of concern about medical non-disclosure. A 2024 research report from specialist broker AllClear found that around one in three UK holidaymakers with medical conditions admitted to withholding information when shopping for travel cover. Consumer advocates argue that the sharp rise in neurodivergent declarations shows how easily travellers can be caught between a wish for privacy and the risk of having claims rejected if they fail to disclose relevant information.
Travel sector commentary also links the trend to long waiting lists for adult ADHD and autism assessments. With hundreds of thousands of people in the UK awaiting formal diagnosis, there is a growing group of travellers whose conditions are under investigation but not yet confirmed, raising complex questions about what they are required to declare when buying insurance.
Rules on disclosure: where neurodivergent conditions fit in
Publicly available guidance from the UK government and regulators treats many neurodivergent conditions as part of a broader category of physical and mental health issues that must be disclosed when purchasing travel insurance. Updated foreign travel insurance advice on the government’s main information portal, last revised in August 2024, states that travellers must declare mental health conditions or risk invalidating their policy and notes that some insurers may exclude treatment linked to a pre-existing mental health condition.
The Financial Conduct Authority’s post-implementation review of travel insurance signposting rules, published in 2024, focuses on “pre-existing medical conditions” without specifically naming neurodivergence. However, industry summaries of the rules confirm that declarations typically cover conditions that appear in medical records or require medication or specialist care, a description that can apply to diagnosed ADHD, autism and associated conditions such as anxiety or depression.
Consumer information services such as MoneyHelper and disability charity Scope advise travellers that any existing health condition, including mental health or disability-related needs, should be declared when obtaining travel insurance quotes. Their guidance explains that insurers will usually ask how a condition affects day-to-day life, what treatment is in place and whether any recent changes or hospital visits have occurred. For neurodivergent customers, that can mean disclosing not only autism or ADHD but also related diagnoses where they could influence the risk profile or the likelihood of a claim.
Commentary in independent explainers on neurodivergent travel insurance notes that official UK documents do not yet spell out, in detail, how insurers should treat ADHD or autism disclosures. Analysts argue that this lack of specific wording leaves neurodivergent travellers reliant on firms’ own medical screening tools and policy wording, making it harder to predict how different insurers will price or underwrite similar disclosures.
Premium shock and access challenges for undiagnosed travellers
Alongside the rise in formal declarations, there are growing concerns about affordability and access for people whose neurodivergent conditions are still under assessment. A 2025 announcement from Co-op Insurance acknowledged that many UK travel insurers will not cover people with “unconfirmed health status,” which can include those on waiting lists for ADHD or autism diagnosis, as well as customers awaiting test results for other serious conditions. In response, the company expanded its travel insurance offering so that an undiagnosed condition would no longer automatically block customers from obtaining cover.
Reports from consumer advocates and disability organisations suggest that other travellers in similar situations can struggle to secure standard cover or face significantly higher premiums. Informal accounts collected by charities and online communities describe people being refused quotes while awaiting ADHD or autism assessments, while others report sharp price increases once they declare a new diagnosis to an insurer.
Regulatory material indicates that UK travel insurers are expected to provide clear signposting to specialist providers where mainstream policies are not suitable for customers with more serious or complex medical conditions. The FCA’s 2024 review of travel insurance signposting rules describes a directory of specialist firms designed to improve access for these customers, though the document does not break out specific figures for neurodivergent conditions.
Advocacy groups have welcomed measures that expand cover for undiagnosed or complex needs but argue that the overall picture remains patchy, with substantial variation in how different insurers design their medical questionnaires and assess risk related to neurodivergence.
Non-disclosure risks and confusion over what to tell insurers
The doubling of neurodivergent declarations is occurring alongside evidence that many travellers remain confused about what exactly must be disclosed. AllClear’s 2024 research into medical non-disclosure reported that a third of respondents with pre-existing medical conditions admitted to being “economical with the truth” when applying for cover, often because they feared their premiums would rise or believed a condition was irrelevant to their trip.
Online discussions among autistic and ADHD communities highlight similar uncertainty. Questions frequently focus on whether travellers must declare conditions that have never caused them to cancel a holiday, whether waiting-list status for assessment counts as a medical issue under investigation and how insurers treat long-standing diagnoses that have recently been added to a medical record. While such experiences are anecdotal, they illustrate the gaps between official policy wording and how consumers interpret disclosure requirements.
Consumer-facing guidance from government-backed services emphasises that failing to declare a condition that appears in medical records or is under active investigation can allow an insurer to treat a policy as invalid. Information published on the government’s travel insurance advice pages warns that undisclosed mental health issues may lead to claims being rejected, even if the claim appears unrelated to the condition, because insurers can argue that they did not have a full picture of a traveller’s health when pricing the policy.
Industry explainers on ADHD and autism travel cover add that non-disclosure can also complicate claims for lost medication or emergency treatment abroad. Where stimulant medicines for ADHD or support needs related to autism form part of the travel plan, failure to declare these elements can make it harder for travellers to recover costs if something goes wrong.
Calls for clearer wording and more inclusive products
The recent spike in declarations has prompted fresh calls for clearer wording in travel insurance questionnaires and policy documents, particularly around lifelong neurodevelopmental conditions. Commentators writing in consumer and disability media argue that many screening tools remain heavily focused on acute medical episodes such as hospital stays or surgery, rather than on differences in cognition or communication that may not fit traditional medical templates.
Some UK insurers have begun marketing dedicated medical travel policies for autism or expanded cover for people with complex mental health needs. Product information from specialist providers states that these policies are designed to cover both the autistic traveller and accompanying family or carers and to factor in common co-occurring conditions such as anxiety, epilepsy or sleep disorders. However, analysts note that these specialist products can be more expensive than standard cover, reinforcing the need for transparent pricing and accessible information about how premiums are calculated.
Accessibility advocates also point to initiatives outside the insurance sector that aim to make travel more inclusive for neurodivergent people, such as training programmes for airlines, hotels and attractions to better support autistic guests. They argue that clearer insurance rules, combined with more inclusive on-the-ground practices, would help reduce the additional administrative and financial burden faced by neurodivergent travellers.
With diagnosis rates rising and waiting lists for assessments remaining long, industry observers expect pressure to grow on insurers and regulators to clarify how neurodivergent conditions should be treated within medical screening and pricing. For now, public guidance continues to stress two central messages for holidaymakers with ADHD, autism or related conditions: read the medical questions carefully and answer them in full, and seek specialist advice if standard policies appear unclear or unsuitable.