
More news on this day
A sharp rise in travel insurance disclosures for ADHD and autism among UK holidaymakers has prompted fresh warnings that neurodivergent travellers risk invalidating cover if they misunderstand medical declaration rules.
Get the latest news straight to your inbox!
Declarations for ADHD and autism almost double
Recent industry data indicate that medical disclosures linked to neurodivergent conditions are rising rapidly in the UK travel insurance market. Specialist provider Staysure reported 4,676 declarations of ADHD and autism among customers aged over 50 between January and July 2026, compared with 2,613 across the whole of 2025. According to coverage in the International Travel & Health Insurance Journal, this represents a 79 percent increase in just over half a year, highlighting shifting awareness and diagnosis patterns among older travellers.
The figures come amid a wider rise in neurodevelopmental diagnoses and waiting lists. Publicly available NHS data show that, as of late 2024, around 213,000 people in England had an open referral for suspected autism, with many waiting more than three months for assessment. Travel insurers and consumer groups note that this growing cohort faces complicated questions when arranging cover, particularly if they are still awaiting formal diagnosis or undergoing investigations.
Analysts suggest that the growth in declared ADHD and autism among over-50s reflects both increased recognition of late-diagnosed neurodivergent adults and closer scrutiny by insurers of mental health and cognitive conditions. For travellers, the trend means more frequent contact with medical screening questionnaires and, in some cases, higher premiums or referrals to specialist providers.
Warning over undeclared or ‘under investigation’ conditions
The surge in declarations has renewed attention on the consequences of not disclosing relevant health information. Guidance from the UK government’s foreign travel insurance advice, updated in August 2024, stresses that travellers must declare pre-existing medical conditions and any pending treatment or tests, warning that failing to do so can invalidate a policy if complications arise on a trip.
Industry press statements from Co-op Insurance in 2024 highlighted that millions of UK residents on waiting lists for ADHD, autism or other conditions under investigation could face large medical bills if they travel without telling their insurer. The company warned that, in some policies, an undeclared investigation noted in a traveller’s medical records could be used as a reason to reject a claim, even if the claim itself is not directly related to the underlying suspected condition.
Consumer advocates report that the phrasing of medical questionnaires is a recurring source of confusion. Questions about “any undiagnosed condition” or “symptoms that are under investigation” can leave neurodivergent travellers unsure whether a referral for an assessment, but no confirmed diagnosis, must be disclosed. Where doubt exists, legal and consumer guidance generally advises disclosing more rather than less, since UK insurance law places a duty on customers to take reasonable care not to misrepresent their health when answering direct questions.
Complaints and confusion around mental health and neurodivergence
Complaints data suggest that misunderstandings over medical declarations are feeding into wider dissatisfaction with travel insurance outcomes. The UK Financial Ombudsman Service reported 4,466 complaints about travel insurance in the 2023/24 financial year, its highest level since the pandemic, with the majority linked to claim denials. Case studies published by ombudsman and mediation bodies show disputes where insurers declined to pay after identifying undeclared health conditions in medical records, including mental health issues.
Research by consumer group Which? in 2024 found widespread uncertainty over what needs to be declared. Survey results indicated that 16 percent of respondents did not realise ADHD medication should be disclosed, while 17 percent said the same about antidepressants. The study also reported that medical expense claims were the most common type of travel insurance claim in 2024, accounting for around one third of all claims, increasing the stakes if cover is later questioned.
Specialist mental health and financial inclusion organisations have previously documented barriers faced by people with mental health conditions when trying to access fairly priced insurance. Reports drawing on earlier Financial Conduct Authority data argued that complex screening processes and opaque pricing deter some consumers from being fully open about their health, particularly when the perceived risk of their condition during a leisure trip seems low to them.
Regulators track vulnerable customers and access to cover
The UK Financial Conduct Authority’s Financial Lives 2024 survey, published in 2025, underlines how health conditions are shaping experiences across the general insurance market. The survey frames long-term physical and mental health conditions, including those affecting cognitive abilities, as a key driver of consumer vulnerability, influencing how people choose and use financial products such as travel insurance.
Selected findings from the survey and related evidence submitted to Parliament show that 81 percent of UK adults hold at least one home, travel or motor insurance product. However, the same evidence notes that complaints and external research point to worsening performance on claims handling across several lines, with travel insurance among the weakest areas. Regulators are tracking the proportion of consumers who say they were declined a product for non-financial reasons, such as health, as part of broader outcomes metrics for 2022 to 2025.
Over recent years, the FCA has introduced signposting rules intended to help customers with serious medical conditions access cover by directing them to specialist providers when mainstream insurers will not offer a suitable policy. Advocacy groups focusing on mental health and insurance have welcomed the changes but questioned whether signposting alone is sufficient for such a large population of people with mental or cognitive conditions, including many neurodivergent adults.
What neurodivergent holidaymakers are being advised to check
As declarations of ADHD and autism rise, travel industry coverage increasingly highlights practical steps for neurodivergent travellers assessing policies. Consumer advice stresses the importance of reading medical screening questions in full, paying particular attention to references to “awaiting diagnosis,” “under investigation” or “specialist referral,” and answering based on any current referrals on record with a general practitioner.
Guidance from government and consumer organisations also recommends checking whether a policy treats autism, ADHD and related conditions as pre-existing medical conditions that must always be declared, or only when they have led to recent hospital treatment, medication changes or trip cancellations. Some specialist insurers indicate that they can cover stable neurodevelopmental conditions at modest additional cost, while others may impose higher premiums or exclusions.
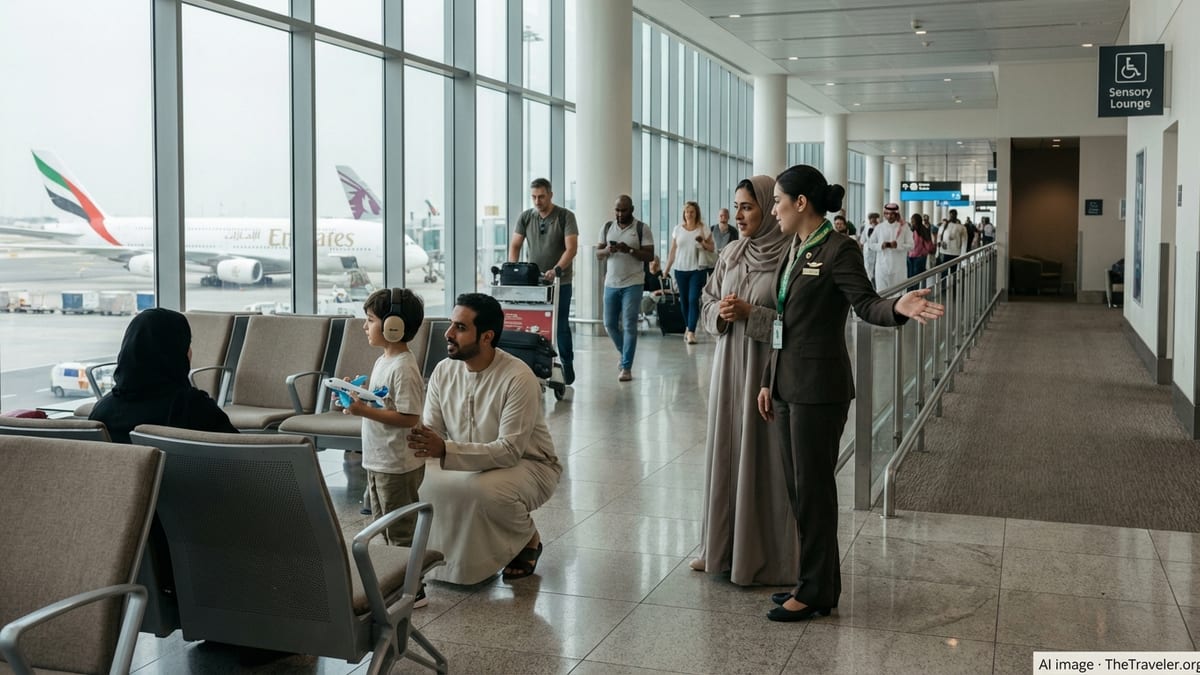
Prospective travellers are further urged to keep written confirmation of medical disclosures and screening outcomes, such as emails or policy schedules that list declared conditions, in case of later disputes. Given the growth in claims and complaints, publicly available information suggests that clarity at purchase stage is increasingly important, particularly where a traveller’s neurodivergent condition could intersect with other mental health, mobility or sensory needs during a trip.