

More news on this day
The U.S. hotel sector is now on track to sell more room nights in 2026 than in any year on record, according to an updated forecast from CoStar’s STR unit and Tourism Economics released on November 20, 2026, a milestone that signals not just recovery from the pandemic but a step beyond it for hotel demand specifically.
Get the latest news straight to your inbox!
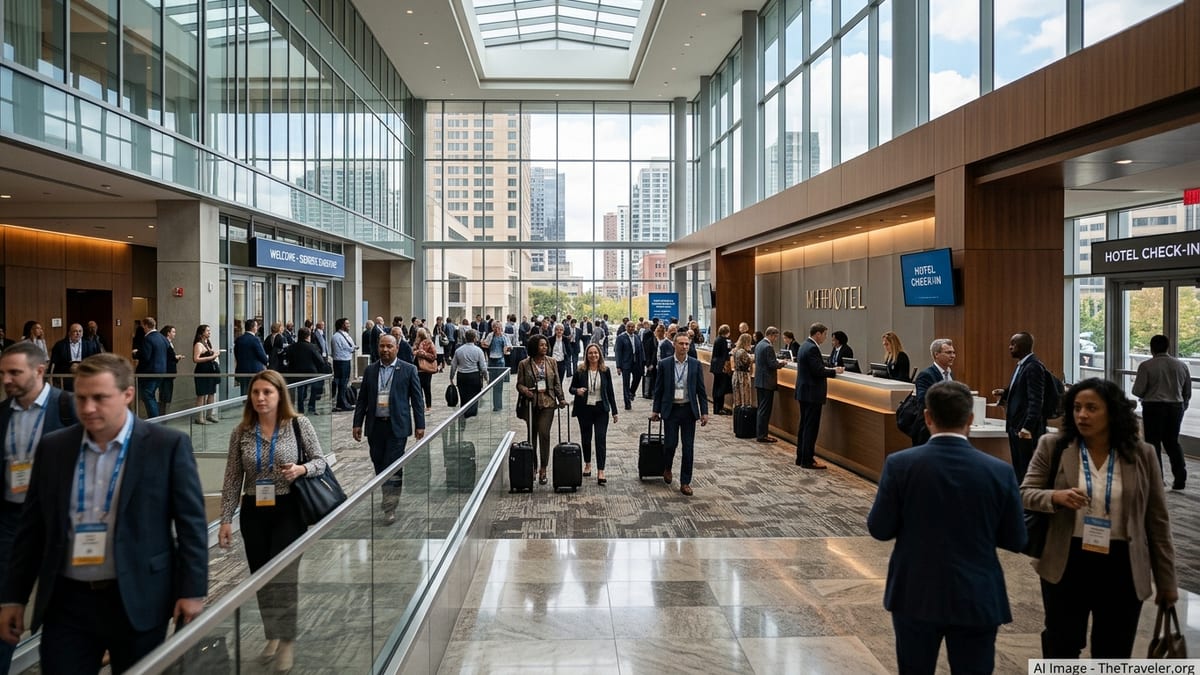
Forecast: 2026 Demand Running Ahead of Pre‑Pandemic Peak
In their final U.S. hotel forecast update of 2026, CoStar and Tourism Economics reported that year-to-date room demand is already above the previous pre-COVID high and that full-year 2026 is now projected to finish at an all-time record for room nights sold. The revision, published on November 20, reflects stronger-than-expected results through early November combined with short-term booking and economic indicators.
The forecast stresses that these are projections based on current data rather than final tallies. CoStar notes that the record will be confirmed, or revised, when STR issues its complete 2026 performance data in early 2027. For travelers, the important takeaway is that hotels are filling more rooms on more nights than at any point since at least 2019, particularly in business and event-driven markets.
A “Historic Fall Run” Confirms Broad Demand Surge
Underlying the upgraded forecast is what CoStar describes in recent STR-based analyses as a “historic fall run” for U.S. hotels. At least 15 individual weeks in 2026 have already set new weekly demand records, the most in any year since 2019, with the 43rd week of the year hitting an all-time high for that specific week. This pattern indicates that demand strength is not confined to a single holiday or major event but has stretched across much of the year.
Revenue per available room, or RevPAR, has risen alongside occupancy rather than in place of it. Recent weekly data show nationwide RevPAR running roughly 5 percent higher than the same period a year earlier, with even stronger percentage gains at midscale and economy properties. That combination of fuller hotels and higher revenue reflects both more travelers booking rooms and hotels successfully charging more for those nights.
Drivers: Group Events, Business Travel and Resilient Leisure
CoStar and Tourism Economics attribute much of the current upswing to a resurgence in group and convention business layered on top of steady leisure demand. Major convention and meeting destinations, including markets such as Nashville and other large event-focused cities highlighted in CoStar’s market commentaries, have seen outsized gains as corporate and association calendars refill.
Data compiled for the U.S. Travel Association’s Travel Recovery Insights show that U.S. hotel room demand in September was up by roughly 5 to 6 percent compared with the same month in 2025, underscoring the momentum that carried into autumn. Broader travel forecasts from U.S. Travel and Tourism Economics suggest that domestic trips are doing most of the work, offsetting weaker inbound international volumes even as overall travel spending, adjusted for inflation, remains under more pressure than room-night counts alone.
FAA Ground Stop Gave a Bump, Not the Underlying Trend
The strong trajectory for hotel demand predates the Federal Aviation Administration’s rare nationwide ground stop in mid-November, which temporarily halted most U.S. departures for several hours after a telecommunications failure. CoStar’s separate analysis of that weekend notes a measurable surge in hotel demand from stranded passengers who needed last-minute rooms as flight cancellations and missed connections rippled through the system.
However, both the new forecast and related commentary from CoStar emphasize that the November ground stop added a short-lived spike on top of already elevated occupancy and revenue levels. Travelers should understand the disruption as an exceptional event that briefly intensified demand in certain airport and hub markets, rather than as the cause of the record-setting path the industry has been on since earlier in the year.
What Travelers Can Expect on Pricing and Availability
For travelers, record-level room demand translates into tighter availability and firmer pricing in many parts of the country, especially around big events and peak leisure periods. Higher occupancies reduce the inventory hotels are willing to discount close to arrival, meaning last-minute bargain hunters are more likely to face higher rates or limited options, particularly in mid-priced and upscale segments where recent RevPAR growth has been strongest.
Cities with heavy group and convention calendars are likely to feel the squeeze most acutely. When large events are in town, business and leisure travelers competing for the remaining rooms can see prices jump and preferred hotels sell out far in advance. In some secondary markets, strong domestic travel and event activity are also narrowing the gap between off-peak and peak pricing, making shoulder seasons less reliably quiet than before the pandemic.
Planning Ahead for 2027 if the Trend Holds
Because the CoStar/STR and Tourism Economics outlook remains a forecast until full-year data are compiled, travelers should watch for STR’s year-end 2026 release in early 2027 to see whether the record is confirmed and how performance varied by city and price tier. The same forecasters will also continue updating their projections for 2027 as booking patterns and economic conditions evolve.
If current demand strength persists, leisure travelers looking at popular 2027 peak periods, such as major holiday weeks or marquee events in convention-heavy cities, may benefit from booking earlier than they might have before the pandemic. Checking citywide event calendars, locking in cancellable rates where possible and being flexible on neighborhood or hotel brand can help maintain options in an environment where hotels, at least for now, are selling more nights than ever before.